
Already approved for an FHA 203(k) renovation loan?
RUMi works with homeowners whose FHA 203(k) loan has already been approved. We manage the approved construction scope with a phase-by-phase schedule, coordinate inspections and trade partners, and keep you informed as each draw is documented and submitted to your lender..
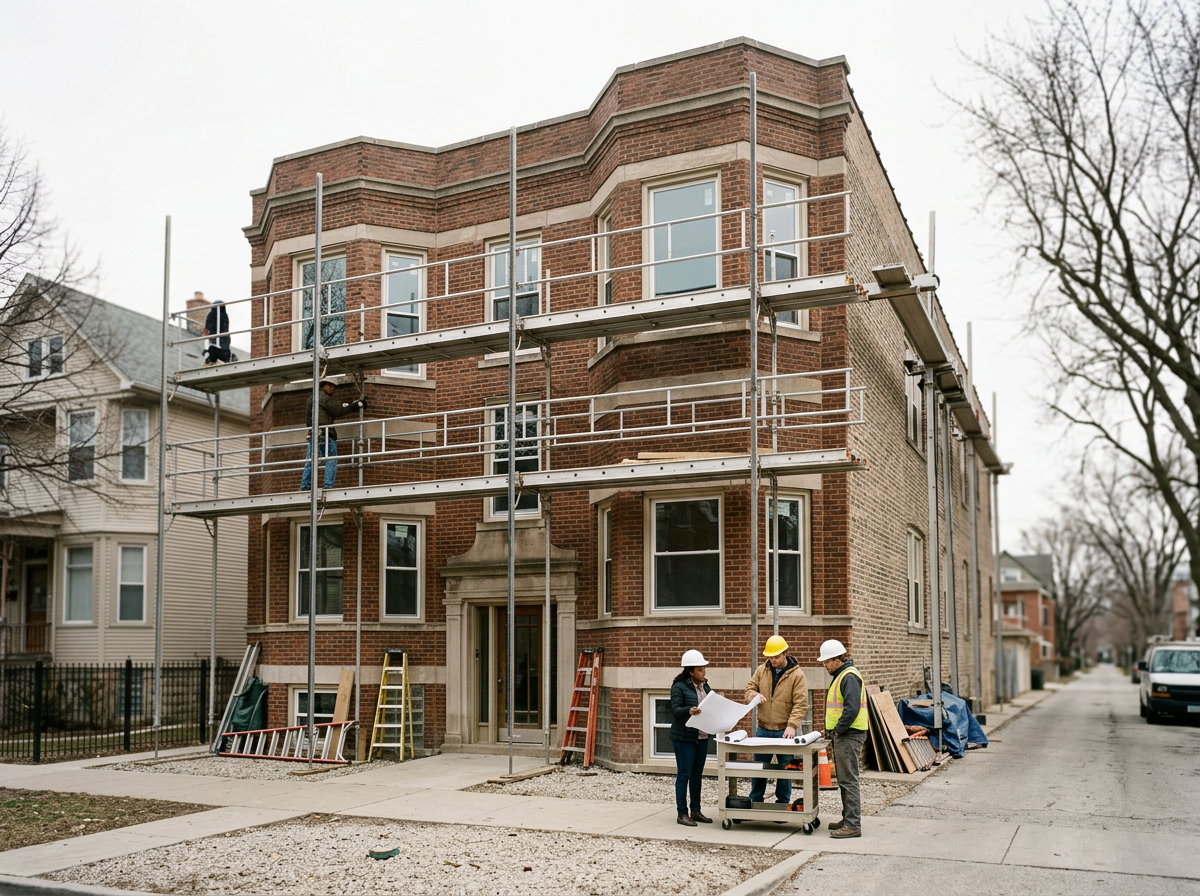
Your 203(k) project, phased and coordinated.
-
No. RUMi is a construction contractor. We work with homeowners whose FHA 203(k) loan has already been approved by a lender. We do not lend, broker, or approve financing.
-
We map the approved scope into clear phases and milestones, with a project schedule or Gantt chart when useful. RUMi coordinates trade partners, permit needs, and inspections with you. Lender and consultant inspection availability and draw processing can affect timing, so we set expectations together and keep you updated.
-
The lender controls the rehabilitation escrow and payment schedule. Under Standard 203(k), HUD requires a check to the borrower and contractor as co-payees unless the borrower gives written authorization at each draw for direct payment to the contractor. Under Limited 203(k), the lender may issue a check solely to the contractor or to the borrower and contractor together. Your lender’s procedures and the loan documents determine the process.
-
No. RUMi does not provide loan funding. Your lender controls what can be released from the rehabilitation escrow and when. We can plan for approved supplier or trade deposits in the project schedule, but any advance or prepaid item must be allowed by the loan documents and confirmed by your lender. Do not assume a deposit will be funded unless your lender confirms it.
-
Yes. We coordinate construction scheduling and required project documentation with you and the appropriate project contacts. The lender controls escrow, funding decisions, inspections, and draw releases; the HUD-approved consultant handles their assigned review and draw inspection duties. RUMi does not make lender or consultant decisions.
-
Have your property address, lender and consultant contact details, approved 203(k) scope or work write-up, and the lender’s contractor and draw requirements available. We can review the construction sequence and discuss whether the project is a fit for RUMi.